If your business filed an extension, it may feel like you bought yourself plenty of time. But an extension is not a bookkeeping strategy. The closer you get to the applicable filing deadline without clean, updated books, the less time remains to resolve missing records, reconciliations, and tax-preparation questions.
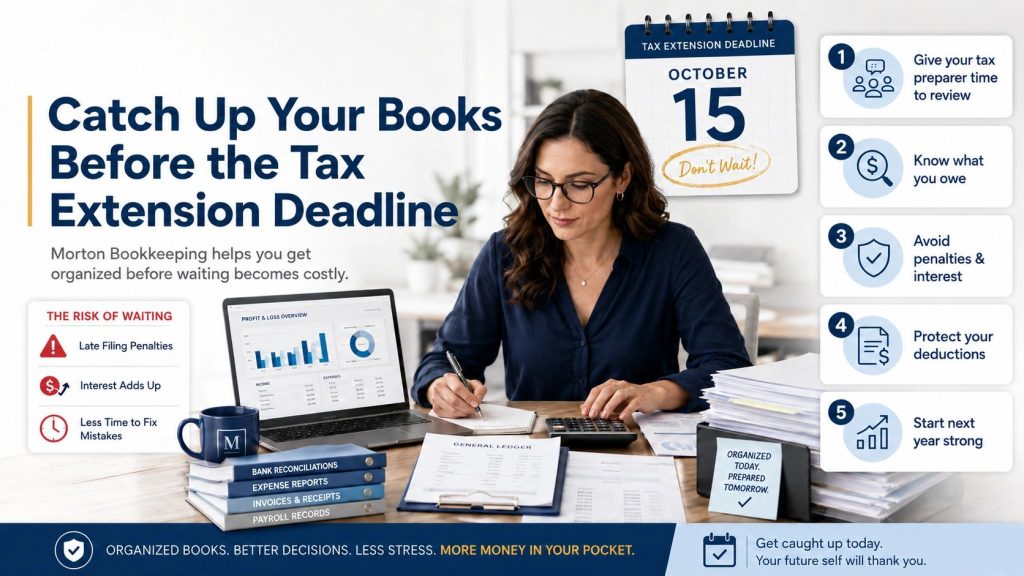
A filing extension changes the filing deadline; it does not automatically change the payment deadline. For many calendar-year individual returns, a valid six-month extension can move the filing deadline from April 15 to October 15. Calendar-year partnerships and S corporations generally have an earlier original due date and commonly use September 15 as the extended filing date under Form 7004. Weekends, legal holidays, and federally declared disaster relief can change those dates. Confirm the return type, tax year, and relief applicable to the taxpayer before relying on a deadline.
That is why waiting until the final weeks creates avoidable pressure. A tax preparer may not be able to finalize a business return accurately while income, expenses, bank and credit-card accounts, loan payments, payroll, owner transactions, and asset purchases remain incomplete or unreconciled. Rushed cleanup can increase the risk of missing support, incorrect classifications, duplicate entries, or unexpected balances due.
Common cleanup issues include unreconciled accounts, personal and business activity mixed together, missing statements or receipts, uncategorized transactions, unresolved payroll liabilities, and loan payments recorded without separating principal and interest. These problems may be fixable, but the work depends on the available records and the client’s response time.
The federal penalty framework depends on the return. When § 6651 applies to a return with unpaid tax, the failure-to-file addition is generally 5% of the unpaid tax for each month or part of a month, up to 25%, and the failure-to-pay addition is generally 0.5% per month, up to 25%. Section 6651(c)(1) coordinates the two when both apply for the same month. Partnership and S-corporation returns are subject to separate late-return penalty provisions calculated by month and by the number of partners or shareholders under §§ 6698 and 6699. Interest on unpaid tax generally runs from the prescribed payment date until payment under § 6601. State rules must be checked separately.
Getting caught up before the filing deadline provides several practical advantages:
- More review time. Current records give the tax preparer more time to identify questions before filing.
- A clearer cash-flow picture. Reconciled books help the owner understand the financial information feeding the return and prepare for a possible balance due.
- Less exposure to avoidable delay. Filing and payment consequences vary by return, but delay can increase penalties, interest, and administrative work.
- Better support for deductions. Section 6001 authorizes recordkeeping requirements; organized source records make business expenses easier to substantiate and review.
- A cleaner starting point for the next period. After prior periods are addressed, monthly bookkeeping can help keep the books current.
A bank balance or a QuickBooks file containing transactions does not establish that the books are complete. Reliable bookkeeping requires account-by-account review against statements and supporting records, with unresolved limitations documented rather than forced.
The practical next step is to identify the return involved, confirm the real filing and payment deadlines, determine how far the books are behind, and gather the records needed for cleanup and tax preparation.
A filing extension can provide more time to file. It does not erase the payment obligation or make disorganized records easier to repair. Starting earlier gives the owner and preparer more control over the filing process, cash flow, and next steps.
Federal authority and current filing guidance
- 26 U.S.C., Subtitle F, Chapter 61, Subchapter A, Part V, § 6072(a) and (b) — original due dates for income-tax returns, including the separate calendar-year rule for partnership and S-corporation returns.
- 26 U.S.C., Subtitle F, Chapter 61, Subchapter A, Part VI, § 6081(a) — authority for a reasonable filing extension, generally not longer than six months except for taxpayers abroad.
- 26 U.S.C., Subtitle F, Chapter 62, Subchapter A, § 6151(a) — tax shown on a return is generally paid at the time and place fixed for filing, without assessment or notice.
- 26 U.S.C., Subtitle F, Chapter 67, Subchapter A, § 6601(a), (b)(1), and (e)(2)(A) — interest on unpaid tax from the prescribed payment date and interest on specified unpaid penalties after notice and demand.
- 26 U.S.C., Subtitle F, Chapter 68, Subchapter A, Part I, § 6651(a)(1), (a)(2), and (c)(1) — failure-to-file and failure-to-pay additions and their coordination when both apply for the same month.
- 26 U.S.C., Subtitle F, Chapter 68, Subchapter B, Part I, § 6698(a)(1)–(2) and (b) — late partnership-return penalty calculated by month and number of partners.
- 26 U.S.C., Subtitle F, Chapter 68, Subchapter B, Part I, § 6699(a)(1)–(2) and (b) — late S-corporation-return penalty calculated by month and number of shareholders.
- 26 U.S.C., Subtitle F, Chapter 77, § 7503, unnumbered operative paragraph — timely performance when the last day falls on Saturday, Sunday, or a legal holiday.
- 26 U.S.C., Subtitle F, Chapter 77, § 7508A(a)(1) and (d)(1) — postponement authority and mandatory minimum postponement period for federally declared disasters.
- 26 U.S.C., Subtitle F, Chapter 61, Subchapter A, Part I, § 6001, first and second sentences of the unnumbered operative paragraph — authority to require records, statements, and returns sufficient to determine tax liability.
Current administrative guidance reviewed September 10, 2026: IRS extension guidance and Instructions for Form 7004.
This article provides general federal information. The correct deadline, penalty, payment rule, and state treatment depend on the taxpayer, entity, return, tax year, facts, and available relief.